

Defiant 1.0 - Our Why
Re-imagining what a venture fund could look like, with a thematically-led, data-driven and product-centric approach to B2B software & fintech investing
Venture has been around since the 1970’s1. Over these past 50+ years, technology has advanced at a blistering pace. The microprocessor was released in 1971 forever changing hardware form-factors. The dot-com bubble of the 1990’s came and went, opening our eyes to this new thing called the internet and how we could conduct business online for the first time. The iPhone was released in 2007, providing a portable computer in all our pockets and another platform to be leveraged by consumers and businesses. Big data became common parlance in the 2010’s and fast forward to 2022 when AI pushed the boundaries even further as to what humans and technology can accomplish. And yet, with all that has happened around it, the product that is Venture has barely changed. The irony is that despite investing in technology businesses, venture funds have been the slowest to adopt it. The industry is stuck in the old world, with most funds operating like 50 year old service providers, rather than the agile tech business they support.
We are here to change that.
We are a team of investors, technologists and builders, who saw first hand how Venture could evolve. We are here to push the boundaries of what a traditional VC fund looks like. To question everything, never accept the status quo, and create something different. We believe founders deserve better, and only by leveraging technology can we reliably deliver value to our companies and superior returns to our investors.
Our approach is three-fold, at its core a mission to productise venture, by creating a fund where data, technology and deep thematic work are integral to everything we do. Like the companies we invest in, we are building products - internally for our team to move faster and make better decisions, and externally to add value to our founders and the wider ecosystem. We are investors first and our products empower us to focus on the things that matter - deep thought, building relationships to win deals, and adding value to our founders.
We have a love for the craft of investing and pride ourselves in our innate curiosities coupled with desire to go deep and discover truths. Our investment style is thematically led, concentrated, and focused on B2B software & fintech. We leverage macro and micro data to craft thought-leading investment theses, with the aspiration to back future category leaders in verticals exposed to long-term secular growth trends. We are here to do the work, be bold, and support our founders with passion.
Some in the industry may reject us. The old guard may resent us. That is what it means to be Defiant - to stand strong in your beliefs, with humility and conviction, in pursuit of a dream. Said best by Howard Zinn
The power of a bold idea uttered publicly in defiance of dominant opinion cannot be easily measured. Those special people who speak out in such a way as to shake up not only the self-assurance of their enemies, but the complacency of their friends, are precious catalysts for change.
Our investment focus
Early stage, but not too early
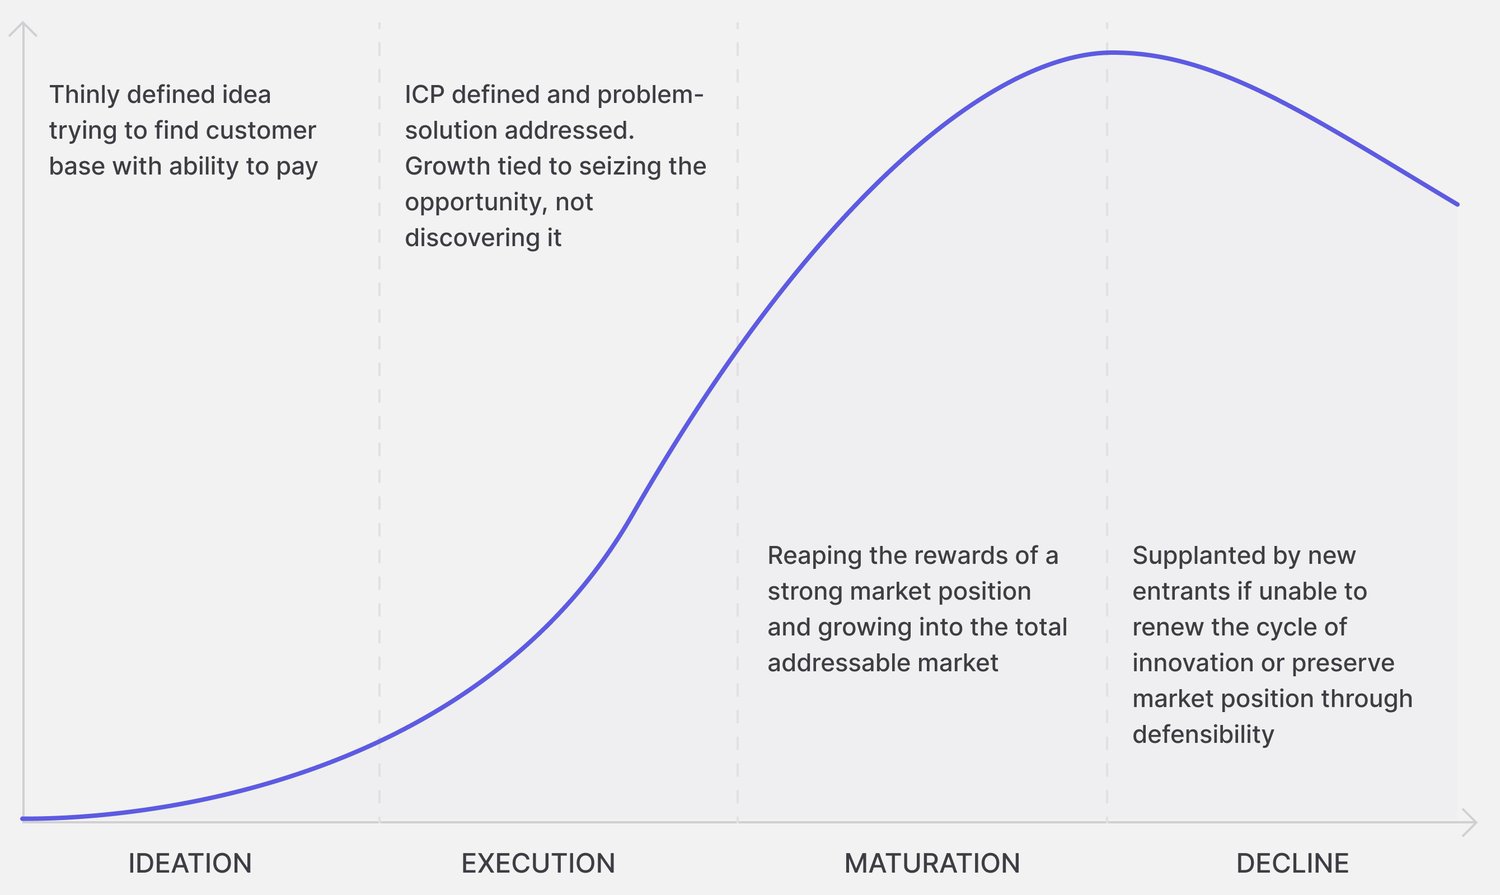
There are four phases to the startup lifecycle - ideation, execution, maturation and decline. We are looking for companies who are traversing the chasm between the first two, those with early signs of product-market-fit. In common vernacular you could refer to them as Late Seed and/or Series A however titles can be misleading, so we focus on fundamentals - these companies typically have a live product in market, a handful of paying customers, and some semblance of a repeatable growth engine. We believe we can uniquely add value to companies of this stage through our product-centric and data-driven approach, becoming partners for the long-term. We can invest anywhere from $2-$10m as a lead, co-lead or follower. We are flexible with a positive-sum mentality, as ultimately it's about finding a structure which works best for the companies, not the investors. We won’t invest in anything pre-revenue or pre-product and our companies have typically raised some form of institutional or professional capital already.
European, with an eye internationally
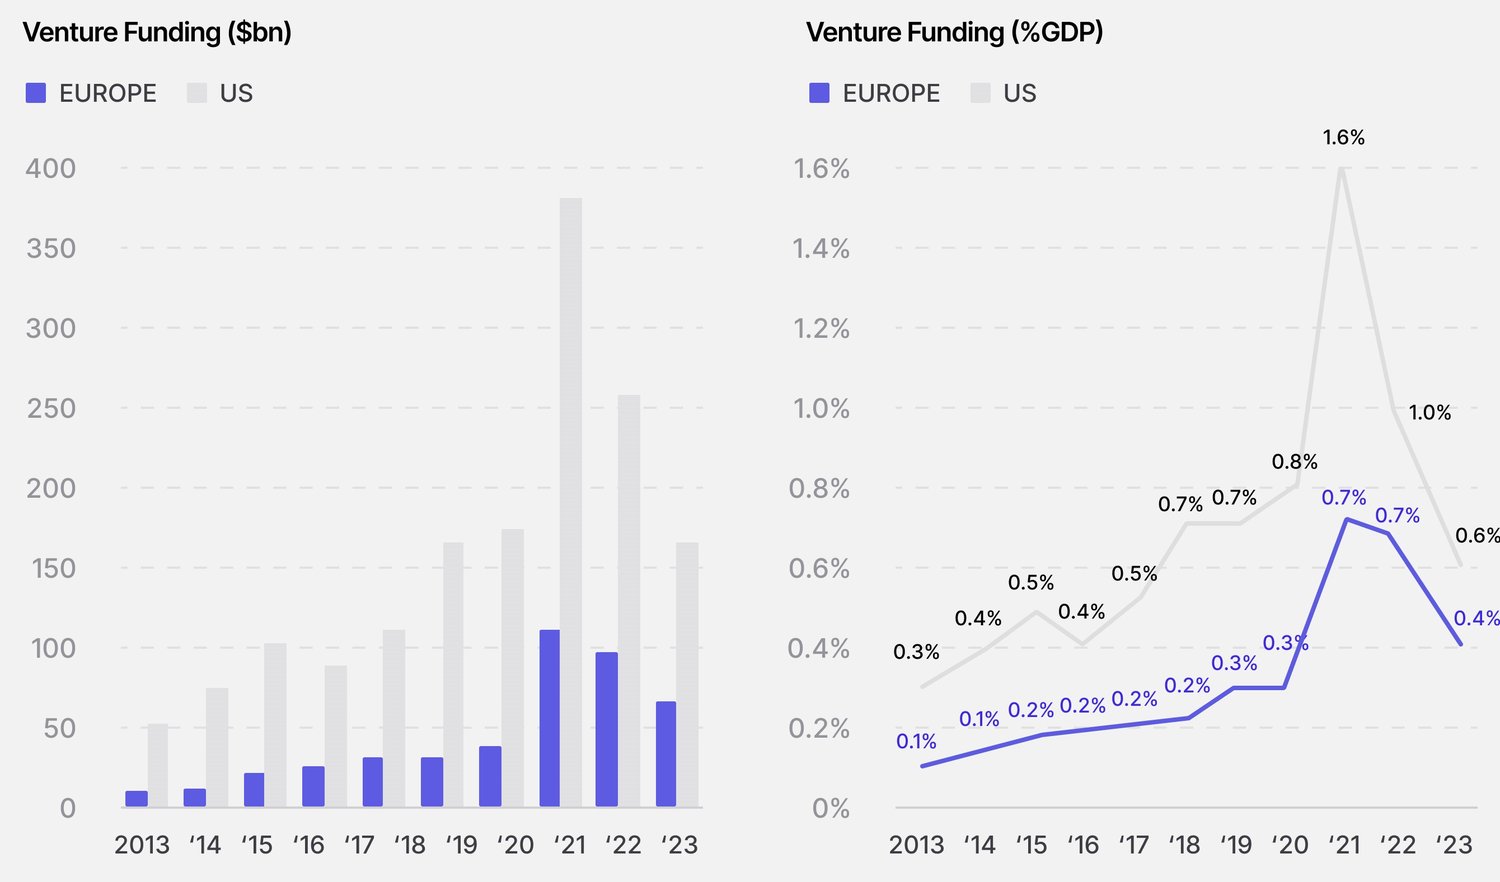
Europe is our home field, it's where we live (London and Lisbon offices), have built our careers, and will be focusing our efforts. The European ecosystem has grown almost 7x in the past decade2, more than double the US (3x), however it still remains structurally underallocated by comparison (2022 US VC Funding represents 1.0% of GDP vs. 0.7% for Europe). Talent density is rising, European companies are becoming more significant on the world stage and we see immense potential in supporting its local champions. It may come as a surprise to many that key European technology hubs like London, Paris, and Berlin account for nearly as many developers as Silicon Valley. From a competitive standpoint, Europe has c.50% fewer VC funds than the United States3 and early stage rounds are typically priced at a +50% discount in Europe4, far more attractive dynamics for investing. Beyond Europe, our thematic approach gives us the ability to look abroad where we believe we have unique insights or a compelling thesis. We will be selectively investing in other developed ecosystems, with an eye on the US and Australia given our team’s personal backgrounds.
B2B Software & Fintech specialists.
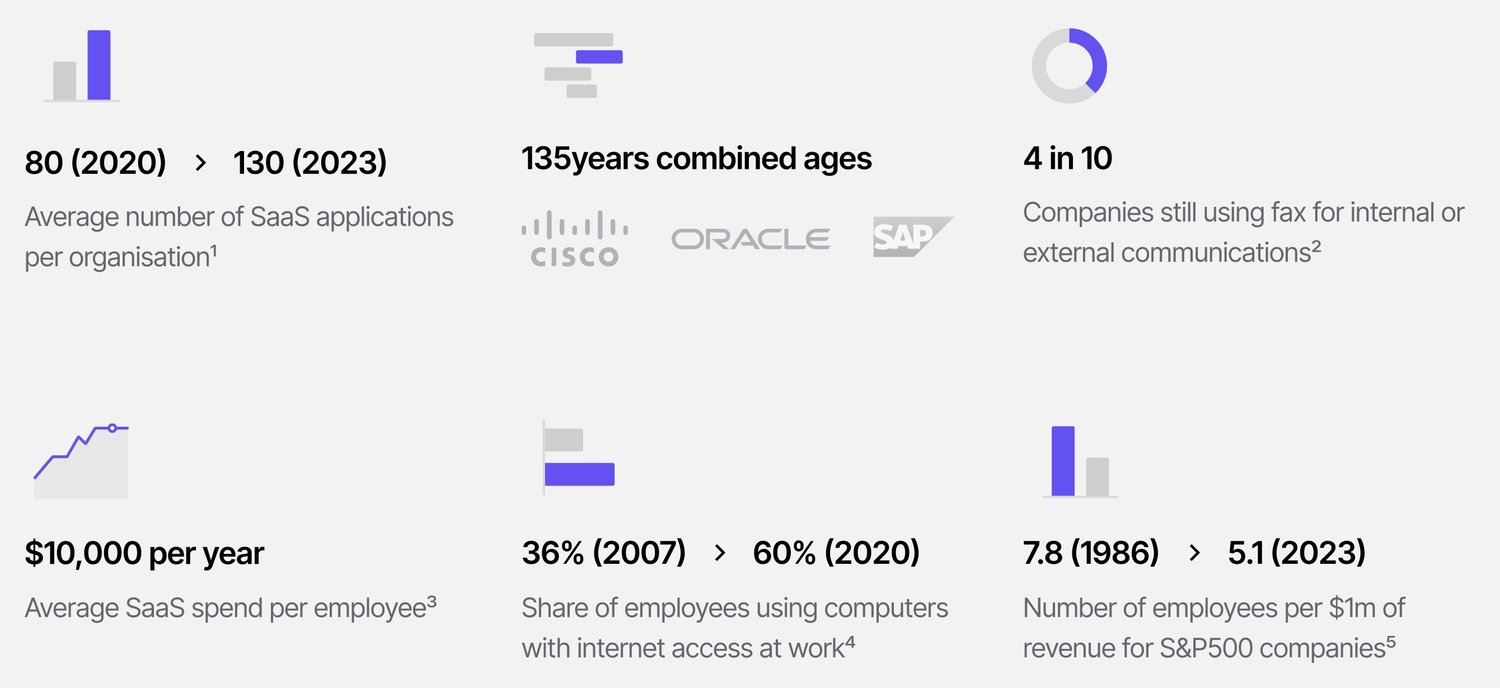
B2B is all we do. We live it and breathe it (we are essentially a B2B software company ourselves). Product, go-to-market, design - we face many of the same challenges as a typical B2B company and speak the same language. Within B2B are focusing exclusively on software & fintech products which are accelerating the digitisation of the enterprise as we believe the next decade of digital transformation will revolve around businesses. Consumers have been spoilt for choice over the past decade - Uber, Airbnb, Spotify, the list of high-grade consumer applications is endless, and we are now starting to demand the same experience in the workforce. Corporates in contrast to consumers have lagged in tech adoption for the longest time, in large part due to lengthy procurement processes, multiple-stakeholders, and the need to prove ROI in a world of budget-based decision making. As demographics shift and tech native millennials & Gen-Z’s become the majority of the workforce5, enterprises will be forced to adopt new technology spurring cycles of investment and the rise of a new generation of tooling.
The Defiant Ones
We are a founding team of two partners, each with a over a decade of experience in financial markets across the spectrum, from venture capital and early stage investing to growth, technology and public markets. We have seen cycles and been fortunate enough to work with 10 unicorns amongst us, giving a view of what great looks like and an understanding of the characteristics in common amongst the most successful teams in the world. We value deep work, intellectual rigor and analytical frameworks. These foundations are complimented with entrepreneurial experience, having each founded businesses of various successes in our past lives (not to mention founding Defiant). We know how challenging the founder journey can be and are here to support in any way we can.
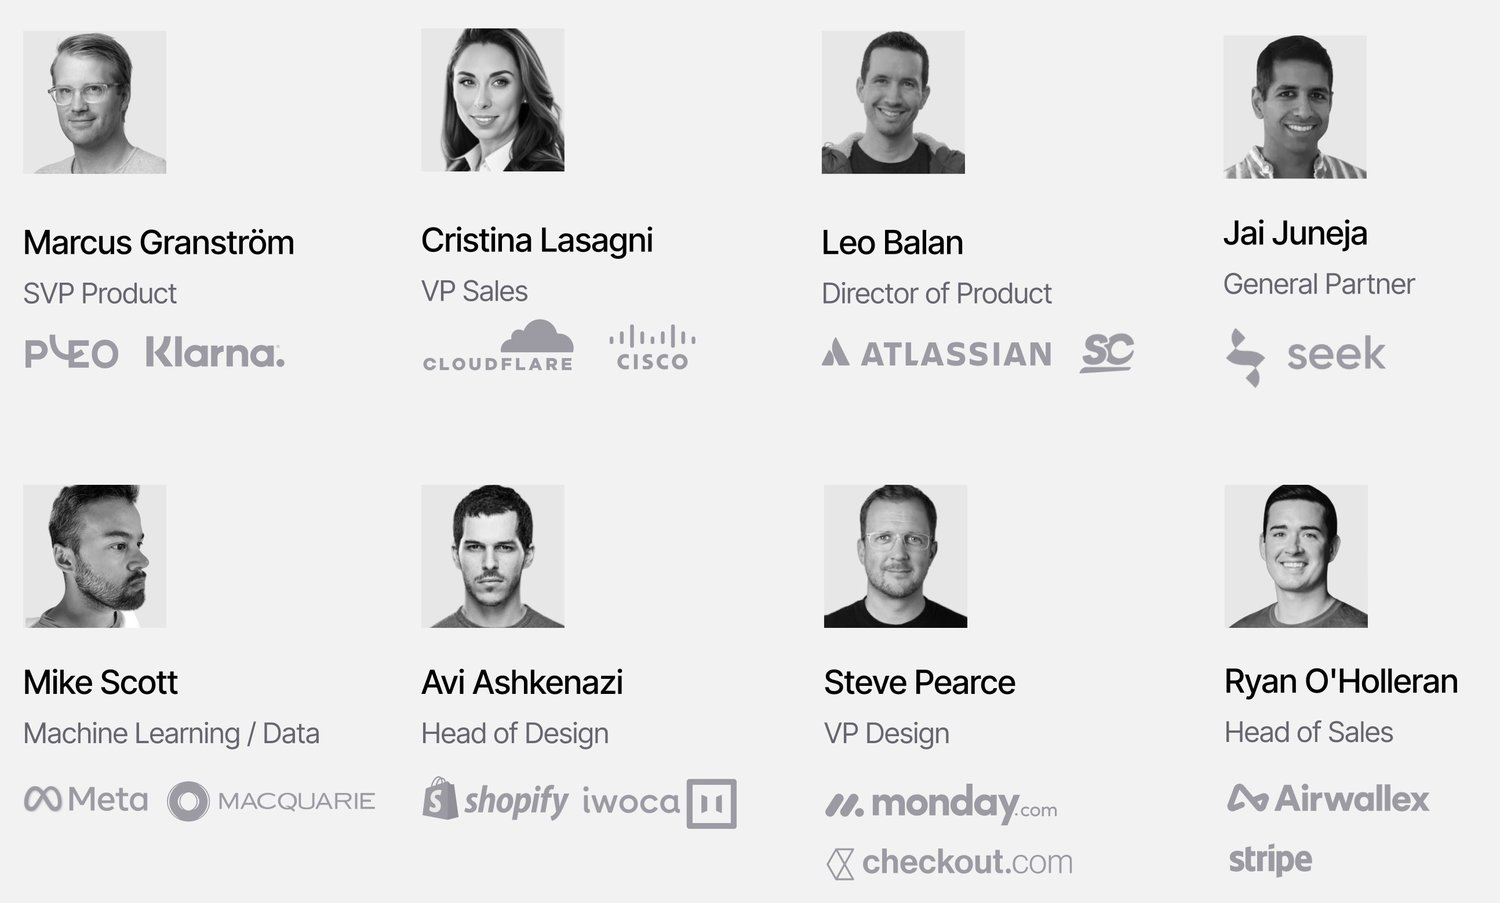
One of the most privileged parts of this job is bringing ambitious people together and engaging in dialogue. From early days we had the aspiration of creating a team of engaged advisors who could provide market intel, help our portfolio founders, and guide us on our product building journey. We see our advisors as an extension of our core team and are incredibly proud of the team we have engaged, coming from some of the most recognised B2B startups in the world - Stripe, Shopify, Atlassian, Checkout.com, Klarna, Pleo, Airwallex - we are privileged to work alongside these individuals and expand our B2B capabilities.
At the end of the day, we are here to support founders and our investments will speak the loudest. As entrepreneurs in venture ourselves, we value grit and determination above all. We look for founders who will run through walls to achieve success, high velocity decision makers, with an eye for detail and often technical nature. Those who will stand true in their beliefs and act as catalysts for change - the Defiant Ones.
Our fund model - concentrated, high conviction
Every aspect of Defiant is deliberate by design and aligned with our goal of delivering one of the best returning funds of our vintage. Contrary to other asset classes, venture is littered with mediocre funds who fail to outperform public market benchmarks. The industry has been flush with cash over the past decade resulting in an imbalance where investing has become more of a popularity contest than thought exercise. We aren’t afraid to draw lines in the sand and strive for something more.
We will be investing in ~20 companies in Fund I. A concentrated portfolio by venture standards. Thought leadership and thematic work takes time, and we don't want to stretch ourselves too thin. Each investment matters to us and is the result of many months of research. Every founder we work with is part of our extended family and we have built high conviction in their capabilities. We believe in the power law, and think ~20 is a sufficient number of shots on goal for it to hold true, given the maths points to ~5% of investments generating ~60% of returns6.
Reserve strategies vary significantly and can have a material impact on overall fund performance. Too large reserves can dilute returns, too few can lead to underinvesting in your winners7. We believe large reserves are the sign of an idle manager and can lead to inefficient capital allocation decisions, where a pool of pre-committed funds is deployed into a set of diminishingly attractive options. We think every follow-on investment should be evaluated on its own merits, and only the best shall survive. Our reserves are capped at 15% of our AuM, a small figure by most venture standards. The goal is to use this capital to double down on only our best performing companies, and should we find ourselves in a fortunate position of running out of reserves (from having many companies perform well), we will work together with our LPs on compelling co-invest opportunities - a more harmonious relationship where incentives are aligned and capital is still available for our businesses who perform.
Pricing discipline can be an oxymoron in venture. Mega cap funds with too much capital, and too low hurdle rates (in part due to the low hurdle rate from their own sources of capital) competing in bidding wars have often led to inflated early stage valuations and a rising tide for all ships. Carta data shows the median US based Series A pre-money valuation has risen from ~$25m in 2020 to ~$40m in 20248 (taken with a grain of salt given the distortions from inflated AI valuations). Some investors have gone so far as to consider entry price irrelevant if the company in question could be a power law outcome. We strive to invest on fair terms, unafraid to walk away from opportunities which are disconnected from reality or become reliant on blue-sky outcomes to deliver acceptable returns. We are looking to maximise first cheque ownership and work with founders who see value in our presence on the cap table, beyond simply the capital we bring. We place a premium on growth, capital discipline and scalable unit economics supporting healthy underlying business models.
The journey ahead
Today is very much day zero for us at Defiant and the road ahead will be arduous. Company building takes time and investing feedback loops can be decades in the making. Our aspiration is to create a multi-generational fund, one which survives beyond its founding members and becomes a reference case in the industry. We have a culture of performance, transparency and trust, with a commitment to put the team above the individual, a duty to seek out the truth, and an infinite mindset where tomorrow's successes are determined by today's actions. We hope to do right by our founders and drive best-in-class returns for our limited partners, without which we wouldn’t be here today and we are endlessly grateful for their support.
The Defiant Team
Footnotes
Sequoia and Kleiner Perkins, two stalwarts of Venture, were founded in 1972. Greylock in 1965 and NEA in 1977
Dealroom data. European VC investment in 2023 of $57bn vs. 2013 of $8bn (c.7x increase). US VC investment in 2023 of $153bn vs. 2013 of $50bn (c.3x increase)
Pitchbook. Data shows 3,760 VC funds with AUM >$1m and HQ in the United States compared to 1,923 with >$1m AUM and HQ in Europe (as of Jan 24’ search)
Pitchbook. Q3 23’ VC Valuations Europe and US. Data shows median early stage pre-money valuation of $40m for US companies vs. €7m for Europe, an 80% discount. The averages are $90m vs. €17m, a similar discount and consistent. We believe the median early-stage European valuation is higher than Pitchbook data is indicating, hence estimating discounts to be closer to the 50% range.
These two demographics will account for c.60% of the workforce by 2030
Sapphire Partners have a well written article on the topic: Dirty Secret: Venture Reserves are Not Always a Good Thing
Carta, State of Private Markets Q1 2024
